EV Häs, LLC Attorney at Law Insights
EV Häs, LLC Attorney at Law Articles
Practical guidance on foreclosure defense, mortgage disputes, debtor rights, and Chicago-area real estate—so you understand your options and next steps.
November 13, 2026
Successor in Interest Rights
What Illinois homeowners and family members should know when a home changes hands after death, divorce, or another qualifying transfer.
November 13, 2026
How foreclosure or bankruptcy can affect escrow
What Illinois homeowners may see from the servicer when the loan is still active, being paid off, or moving toward termination.
November 13, 2026
When a Foreclosure Is Based on a Due-on-Sale Clause
A transfer issue can change the usual servicing-rule analysis for Illinois homeowners.
November 13, 2026
When a servicer says it is exempt
How CFPB mortgage-servicing carveouts work for Illinois homeowners facing foreclosure
November 12, 2026
Foreclosure and a Complete Application
How federal Regulation X timing rules can pause the foreclosure track for Illinois homeowners
November 12, 2026
Default Judgment, Then What?
Illinois homeowners may still have a procedural path to ask the court to reopen a foreclosure case after default.
November 12, 2026
Use the Fastest Error-Dispute Path Before the Sale
When a mortgage servicer makes a mistake, a written notice of error can trigger the servicing review process quickly. If foreclosure is involved, timing matters most.
November 12, 2026
What the CFPB Says Must Happen Before Foreclosure Starts
A practical guide to early-contact and written-notice rules for Illinois homeowners with covered mortgage loans
November 11, 2026
What to bring to 17th Circuit foreclosure mediation
A homeowner-focused checklist based on the court’s accessible mediation materials
November 11, 2026
Ask for Mediation in a Pending Foreclosure Case
In Illinois, the process often depends on your county’s local program and where your case stands in court.
November 11, 2026
Rule 99.1 and Illinois foreclosure mediation
What changed, what stayed local, and how the process fits together now
November 11, 2026
Foreclosure Mediation in Illinois
A county-by-county process, not a single statewide rule
November 10, 2026
Read the order before relying on a move-out date.
A sale date is not a complete possession timeline. Gather the confirmation order, possession provisions, and occupant information for prompt legal review.
November 10, 2026
The statements may stop. Keep the record.
Review a notice suspending mortgage statements carefully. Keep the balance, fee history, and lien documents together before assuming the debt disappeared.
November 10, 2026
The claim is approved. Map how the repair money moves.
A joint insurance check can require coordination with your mortgage servicer. Organize endorsement instructions, repair milestones, and release records.
November 10, 2026
The loan is paid. Finish the escrow reconciliation.
Track the remaining escrow balance after paying off your mortgage. Compare the payoff, final disbursements, refund, and any agreed transfer to a new account.
November 9, 2026
The final agreement deserves a careful comparison.
Review the final modification packet against the offer, payment history, and household budget. Clarify differences and preserve the completed agreement.
November 9, 2026
A sale date is not the whole court record.
A judicial sale and its confirmation are separate steps. Gather the report, notices, and court orders promptly when a confirmation hearing is approaching.
November 9, 2026
Escrow is closing. The property bills still need a plan.
Closing escrow changes how property bills are handled. Organize the notice, upcoming due dates, and payment responsibilities before the transition.
November 9, 2026
Your payment has more than one date.
A bank withdrawal and a mortgage credit date can differ. Build a payment timeline before disputing a late charge or an overdue account entry.
November 7, 2026
Understand the reserve behind the escrow balance.
An escrow cushion is a reserve in the account calculation. Check the projected bills, applicable limits, and lowest balance before disputing the amount.
November 7, 2026
An unavailable-records response needs a closer read.
Review an unavailable-records response against your original request. Identify what is missing, the stated reason, and a focused follow-up question.
November 7, 2026
Stop rebuilding your mortgage story on every call.
Keep mortgage assistance conversations organized. Identify the assigned contact, track callbacks, and connect each request to the documents already submitted.
November 7, 2026
A new hardship needs a clear account history.
A prior mortgage assistance review does not answer every later request. Organize the payment history, previous decision, and new hardship before reapplying.
November 6, 2026
A delayed payoff quote needs a clear follow-up.
Waiting for a mortgage payoff statement? Track the written request, confirm the payoff date, and coordinate with your closing team before sending funds.
November 6, 2026
Match the notice to the property-charge record.
Received a reverse mortgage property-charge notice? Match tax and insurance bills to payment records, verify the recipient, and organize a focused response.
November 6, 2026
Verify the surplus before relying on a number.
A foreclosure sale price does not establish money owed to a former owner. Review sale records, court orders, claims, and distribution requirements.
November 6, 2026
Prepare for the first mediation conversation.
Organize court notices, mortgage records, financial information, and questions before seeking help through Cook County’s foreclosure mediation program.
November 5, 2026
A changed statement needs a careful reading.
A mortgage statement may change during or after bankruptcy. Review the account with counsel before interpreting missing bills or unfamiliar payment categories.
November 5, 2026
A letter offering help still needs a response plan.
An early mortgage assistance letter is a starting point, not an approval. Verify the sender, gather records, and ask clear questions about the next step.
November 5, 2026
Read the explanation behind the decision.
A no-error response should explain the decision. Learn how to request the records relied on and organize a focused follow-up for your Illinois mortgage.
November 5, 2026
One old fee should not create an endless chain.
Review recurring mortgage late fees with a payment timeline. Learn what fee pyramiding means and what Illinois homeowners should ask the servicer.
November 3, 2026
A lump sum needs a plan before it leaves your account.
A large principal payment and a lower monthly payment are not the same thing. Ask these questions before committing savings to a mortgage recast.
November 3, 2026
Military service changes the questions to ask.
Military service may affect mortgage interest and foreclosure protections. Gather the right dates and documents before assuming a particular protection applies.
November 3, 2026
The name on the statement may not be the owner.
Identify the company handling payments and the owner of your mortgage, then keep the right contact information with your Illinois homeowner records.
November 3, 2026
An escrow refund deserves a closer look.
An escrow refund is not a mortgage payoff. Learn what to review in the analysis, payment history, and next payment before spending the check.
November 2, 2026
Preparing a CFPB Mortgage Servicing Complaint: A Homeowner Checklist
A clear timeline and a specific request make a complaint easier to understand. Court deadlines still need separate attention.
November 2, 2026
Mortgage Payment Deferral: What Happens to the Missed Payments?
Moving an amount to later can provide breathing room, but the written terms still matter.
November 2, 2026
Reading Your Mortgage Statement When You Are Behind on Payments
The amount due is only one part of the story. Use the statement to identify questions before you make a payment decision.
November 2, 2026
How to Request Mortgage Records Before a Foreclosure Dispute
A focused written request can help you understand the account, identify missing records, and prepare for a useful legal consultation.
October 30, 2026
Get help without losing track of your account.
A trusted helper may need written permission to discuss your mortgage. Check the form, scope, delivery, and ongoing communications.
October 30, 2026
A familiar email is not enough to verify a wire.
An urgent email can imitate a trusted professional. Use independently verified contacts before transferring mortgage or closing funds.
October 30, 2026
The last payment may be much larger.
A large final mortgage payment needs more than a hoped-for refinance. Verify the maturity date, amount, and practical alternatives early.
October 30, 2026
Your deposits are only part of the income story.
Prepare a consistent income record for mortgage assistance without confusing business deposits, business expenses, and household cash flow.
October 29, 2026
A repair emergency needs a mortgage plan, too.
An insurance claim and mortgage assistance are separate processes. Keep repair costs, payment instructions, and servicer communications organized.
October 29, 2026
Moving out does not close the mortgage file.
A household agreement, property title, and mortgage obligation are different records. Review each before assuming someone else has handled the loan.
October 29, 2026
Can your budget carry the catch-up payment?
A catch-up plan can temporarily raise your mortgage payment. Compare the written schedule with a realistic budget before committing.
October 29, 2026
A grace period is not a new due date.
Separate your mortgage due date, late fee window, and payment receipt so a timing problem does not become a recurring shortfall.
October 28, 2026
A default letter is a reason to act—not to guess.
Identify what the letter actually requires before treating it as a routine bill or a court order.
October 28, 2026
One home. Two loans. Two separate records.
A current first mortgage does not answer every question about a second loan secured by the same property.
October 28, 2026
A recorded notice is a starting point—not the whole case.
Connect the property record to the actual court file before drawing conclusions about your home.
October 28, 2026
The sale price is not the amount you get to keep.
Build a realistic closing calculation before relying on a home sale to solve mortgage arrears.
October 27, 2026
A VA-backed loan still needs an early payment plan.
If a payment is becoming difficult, organize the facts and use the official assistance channels before relying on a program name or a promise.
October 27, 2026
You paid into escrow. The tax bill still shows unpaid.
Trace the specific installment instead of assuming either the county or the mortgage statement tells the whole story.
October 27, 2026
The borrowing period ends. The payment may change.
A familiar HELOC bill is not a promise that the next phase will cost the same. Read the transition notice before the new amount strains your budget.
October 27, 2026
Is PMI still part of your mortgage payment?
Before accepting the charge as permanent, identify the kind of mortgage insurance you have and ask which cancellation requirements apply.
October 26, 2026
A partial claim is help with arrears, not erased debt.
If your FHA servicer proposes a partial claim, look beyond the immediate payment relief. Understand the separate obligation and how it may affect a later sale or refinance.
October 26, 2026
Scheduled is not the same as paid.
An automatic-payment setting can look reassuring while a transfer is pending, rejected, or applied differently than expected. Trace the transaction before guessing what happened.
October 26, 2026
Explain what changed. Show where things stand now.
A hardship explanation works best as a clear account of your situation, not an emotional sales pitch or a copied promise. Start with the actual instructions for your loan.
October 26, 2026
Your income changed. Start before the payment is missed.
A smaller paycheck can become a housing problem quickly. A clear picture of the shortfall makes the first conversation more useful than waiting for an overdue notice.
October 23, 2026
An offer to save your home deserves a closer look.
A convincing letter or confident caller is not proof that a mortgage relief offer is legitimate. Slow the decision down enough to verify the person, the service, and the documents.
October 23, 2026
The statement looks wrong. Make the discrepancy clear.
A missing payment, unexplained charge, or conflicting account history deserves a specific review. A dated record can make the issue easier to investigate than another general complaint by phone.
October 23, 2026
A credit alert is the starting point, not the whole record.
If mortgage information appears inaccurate, compare the actual report with the account documents before deciding what to dispute. Clear dates and evidence matter more than a general claim that the score is wrong.
October 23, 2026
The payment pause is ending. What happens next?
A forbearance agreement gives you a defined period of relief. The next step is to understand the unpaid amount, your current budget, and the written arrangement that will govern payments afterward.
October 22, 2026
You do not have to organize mortgage trouble alone.
A HUD-approved housing counseling agency can help you understand the financial picture and prepare a practical plan. Know how to find one, what to bring, and when a legal issue needs separate attention.
October 22, 2026
A modification was denied. Start with the reason, not a new guess.
A denial letter may leave more questions than answers. Illinois homeowners should identify what was evaluated, what the decision says, and whether a response or appeal process applies.
October 22, 2026
A trial payment plan is a step. Confirm what comes after it.
An offer can feel like the problem is finally solved. Illinois homeowners should still track the plan’s requirements, the payments received, and the documents needed to complete a permanent modification.
October 22, 2026
Your mortgage rate is changing. Read the notice before the new payment arrives.
An adjustable rate reset can affect a household budget even when payments have been on time. Illinois homeowners can use the notice to identify what changes, when it changes, and which questions need an answer.
October 21, 2026
Inherited a home with a mortgage? Start with three separate questions.
Who owns the property, who can communicate with the servicer, and what is happening with the loan are connected but not identical. A clear starting file helps Illinois families avoid decisions based on incomplete information.
October 21, 2026
Your mortgage includes insurance you did not choose. Start with the coverage dates.
A force-placed insurance charge can create confusion and a larger bill. Illinois homeowners should separate an actual coverage gap from missing proof or an escrow payment issue.
October 21, 2026
Money left your bank. Why does the mortgage still show past due?
A payment can reach the servicer without being applied as a full monthly installment. Understanding partial payments and unapplied funds helps Illinois homeowners ask the right questions before the account falls further behind.
October 21, 2026
New mortgage company. Same loan. Check the handoff.
A new payment portal can create more than a login problem. Illinois homeowners should verify where the next payment goes, what records transferred, and whether a pending assistance request is still moving.
October 20, 2026
You sent the mortgage documents. Is your application actually complete?
Uploading a packet and completing an application are not always the same thing. This checklist helps Illinois homeowners organize the request, confirm what remains missing, and avoid confusing a servicer review with a court deadline.
October 20, 2026
Bringing the loan current is not the same as paying it off.
A mortgage statement, a reinstatement quote, and a payoff statement can show very different amounts. Before moving money, Illinois homeowners need to understand what each figure is intended to accomplish.
October 20, 2026
Your first foreclosure consultation does not need a perfect file.
It needs the right starting information. For Illinois homeowners, a short timeline, complete notices, and a clear goal can make the conversation more useful, whether the first missed payment is recent or a lawsuit has already begun.
October 20, 2026
Your mortgage payment went up. Start with the escrow breakdown.
A higher payment does not always mean your interest rate changed. For Illinois homeowners, taxes, insurance, and an escrow shortage can each affect the total. Here is how to separate those numbers before the increase becomes a larger problem.
March 18, 2026
You found open building code violations on a Chicago property. Here is how to tell what actually matters
This is where people lose time. They search the address, see violations, and immediately assume the deal is dead or the problem is huge. Sometimes it is. A lot of the time, the real issue is not the violation itself. It is not knowing which record matters, what is still active, and what still needs to be fixed on paper.
March 16, 2026
One bad rehab loan should not wipe out the rest. What Illinois private money lenders need in their documents
This is where private money lenders get hurt. The borrower has multiple projects, one goes sideways, and suddenly you realize your documents were written deal by deal instead of relationship by relationship. Here is what that mistake costs, what a stronger document stack usually covers, and why early legal review saves time in Illinois.
March 11, 2026
You got foreclosure papers in Chicago. Here is what to do this week
When the papers show up, most people freeze. That is normal. The smartest move is not panic, and it is not denial. It is getting organized fast so you can choose a path that fits your stage and your goal.
March 5, 2026
Someone is living in your vacant property in Illinois. What you can do next
This is one of those moments where speed matters, but the first move can either solve the problem or make it worse. The key is figuring out whether you are dealing with a tenant situation or a criminal trespass situation, then taking the right path from there.
March 3, 2026
Mechanic’s liens in Illinois can freeze your sale or refinance. Here is what to know
This is one of those problems that feels small until title gets involved. A contractor says they are owed money, a lien gets recorded, and suddenly your closing or refinance is on pause. Here is what usually triggers a mechanic’s lien, what it can block, and why early legal review saves time.
March 2, 2026
You started work without a permit in Chicago. Here is what happens next
This happens all the time. A small rehab turns into a stop work order, then the timeline blows up. This guide walks you through what the City record usually shows, how to calm the situation down, and how to get back to work the right way.
February 25, 2026
Building Code Violations in Chicago: What the Notice Means and What to Do Next
A building code notice can escalate fast if you ignore it. This guide explains how Chicago violations are issued, how the hearing process works, how to look up your record by address, and how owners and investors protect timelines and cash flow with clean documentation.
February 23, 2026
The Closing That Almost Collapsed: A Chicago Title Surprise
This is a fictional story built from common patterns we see in Chicago real estate. It is designed to teach you how title problems surface, why timing matters, and what a smart pre closing checklist looks like when a deal is on the line.
February 20, 2026
Lease Renewals and Notices in Chicago: Best Practices That Avoid Costly Mistakes
Renewals, nonrenewals, and five day notices feel simple until timing or paperwork is wrong. This guide explains what Chicago and Cook County rules often require, how to document notices correctly, and how housing providers protect cash flow while staying compliant.
February 17, 2026
Emergency Injunctions in Chicago: How Temporary Restraining Orders Work in Illinois
When a dispute is moving faster than the court calendar, an injunction can pause the harm while the case is decided. This guide explains what Illinois judges look for, what filing in Cook County can involve, and how to prepare if you need urgent relief.
February 16, 2026
Bankruptcy vs. Foreclosure in Illinois: A Comparison
When foreclosure shows up, bankruptcy can change the timeline. But it is not a magic reset.
This guide breaks down what each path is designed to do, what people often misunderstand, and how to choose the next step without panic.
February 13, 2026
Deed in Lieu of Foreclosure in Illinois: When It Helps and When It Backfires
A deed in lieu can feel like the clean, quiet exit. Sometimes it is. Other times it backfires because of junior liens, paperwork gaps, or a lender that simply will not accept it.
This guide explains what lenders usually want, why second liens change everything, and how to decide if deed in lieu is a smart move for your Illinois timeline.
February 12, 2026
Selling a Home During Foreclosure in Illinois: How It Works and Common Deal Killers
Selling is not giving up. For many Illinois homeowners, a well timed sale is leverage: it can protect equity, reduce damage, and create a clean exit before the case tightens around deadlines.
This guide explains how selling during foreclosure works in real life, what you must coordinate, and the deal killers that blow up closings when time is short.
February 11, 2026
2 to 4 Unit Owners in Trouble: Tenant Issues During Foreclosure in Illinois
If you are a small landlord facing foreclosure, tenant problems can explode fast: rent gets messy, repairs get delayed, and one bad decision can create a second lawsuit on top of the foreclosure.
This article is for Illinois 2 to 4 unit owners who want to avoid expensive mistakes and keep the case, the building, and the tenant situation under control with calm, document first choices.
February 10, 2026
Reverse Mortgage Foreclosure: The Triggers Families Don’t Expect
Reverse mortgages can be a relief for seniors, but families are often blindsided by what counts as a “default.” It is not always missed payments. In Illinois, the most common problems are taxes, insurance, occupancy rules, and paperwork after a borrower passes away.
This guide explains the triggers in plain English and gives you a calm checklist to protect time, options, and the home.
February 9, 2026
Behind on HOA Dues and Now You’re Facing Foreclosure: What to Know in Illinois
HOA and condo notices are easy to ignore until they stop being “just letters.” In Illinois, unpaid assessments can turn into a recorded lien and, in some cases, a foreclosure lawsuit that complicates everything else—especially if you’re already behind on your mortgage.
This guide explains how HOA pressure intersects with mortgage foreclosure, what the notices usually mean, and how to reduce risk with calm, document-first next steps.
February 6, 2026
Foreclosure Scams in Illinois: “Rescue” Offers, Fake Lawyers, and Title Tricks
When foreclosure pressure hits, scammers show up fast with a promise that sounds like relief: “We can stop the sale,” “We’ll negotiate for you,” or “Just sign here and you’ll be protected.”
This article breaks down the most common Illinois foreclosure scams, the red flags people miss, and how to verify real help before you sign anything or hand over documents.
February 5, 2026
Deficiency Judgments in Illinois: When the Bank Can Still Come After You
After a foreclosure sale, many people assume the debt disappears with the house. Sometimes it does. Sometimes it doesn’t.
A deficiency judgment is the court’s way of keeping the remaining balance alive. This article explains what that means in Illinois, why it matters for your exit strategy, and what to ask a lawyer before you make a rushed decision.
February 4, 2026
Judgment of Foreclosure in Illinois: What It Means (and What It Doesn’t)
The word “judgment” sounds final. In an Illinois foreclosure, it’s usually a turning point, not the end of the road.
This guide explains what a judgment typically changes, what it does not change, and why strategy often shifts at this stage.
February 3, 2026
Illinois Sheriff’s Sale: What It Is, What People Get Wrong, and What Options May Still Exist
A sheriff’s sale feels like the end of the story, which is exactly why people panic and make expensive decisions fast.
This guide explains what a sheriff’s sale actually is in an Illinois foreclosure, what the timeline feels like when it’s real, and why smart last-minute planning can still protect options.
February 2, 2026
Servicer Errors That Push People Into Foreclosure (And How to Document Them)
Most homeowners do not “choose” foreclosure. Sometimes it starts with something smaller that snowballs: a payment that gets applied wrong, an escrow mix-up, insurance charges that appear out of nowhere, or a document packet that mysteriously goes missing.
This guide shows what these servicer errors look like in real life and how to build a clean paper trail so you can protect your options in Illinois.
January 30, 2026
Dual Tracking in Illinois: When Your Servicer Negotiates and Forecloses at the Same Time
It happens more than people expect: you’re uploading documents for “review,” getting hopeful updates, and then a court notice shows up anyway.
Dual tracking is what it looks like when the loan-modification conversation keeps moving while the foreclosure case keeps moving too—and homeowners get crushed in the gap.
January 28, 2026
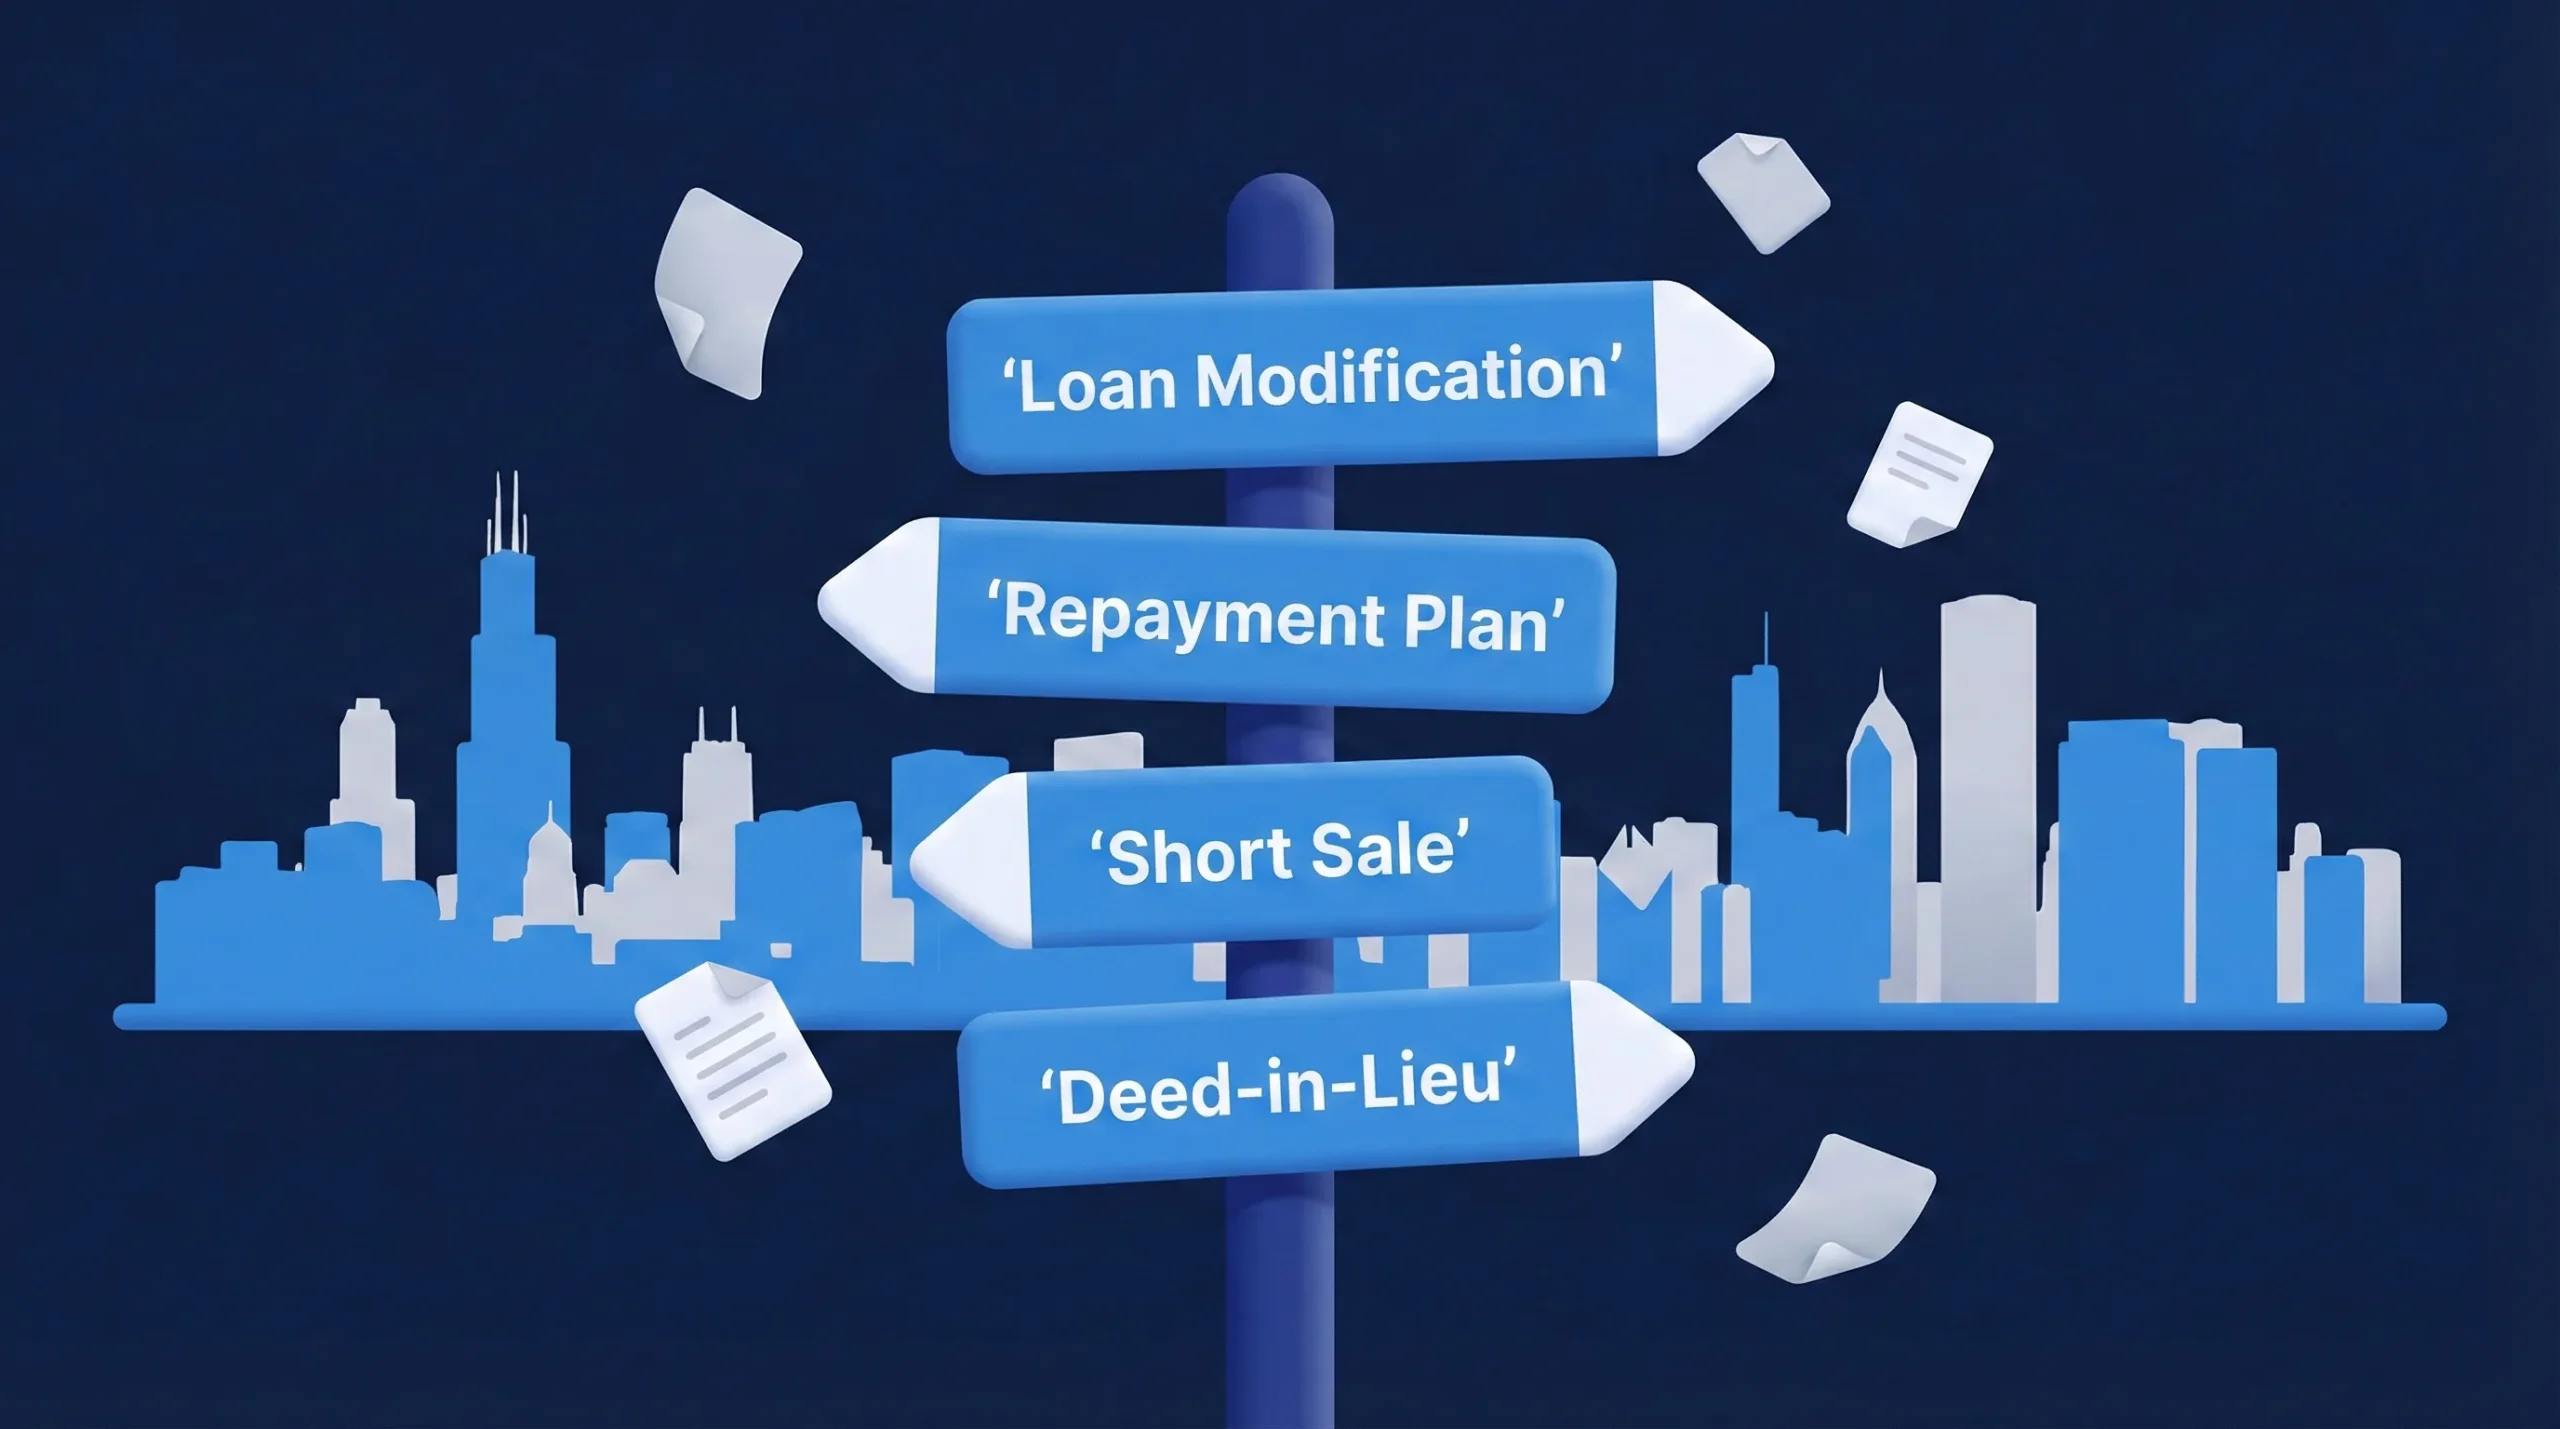
Loss Mitigation (Illinois): Modification, Repayment Plan, Short Sale, Deed-in-Lieu
If you are behind on payments in Illinois, “loss mitigation” is the menu of options that can keep a bad month from turning into a foreclosure case.
This guide explains the four paths homeowners ask about most, what each one usually requires, and how to choose the option that fits your timeline.
Call (312) 775-0980 or request a free case analysis for clear next steps.
This guide explains the four paths homeowners ask about most, what each one usually requires, and how to choose the option that fits your timeline.
Call (312) 775-0980 or request a free case analysis for clear next steps.
January 27, 2026
Mortgage Forbearance Ending? What to Watch Before It Turns Into Foreclosure
If your mortgage forbearance is ending and your payment is about to change, this is the moment to get organized. In Illinois, the fastest way to lose options is to wait until a lawsuit is filed.
Call (312) 775-0980 or request a free case analysis to get clear next steps based on your documents and timeline.
January 26, 2026
How Foreclosure Mediation Works in Illinois (and When It Helps)
If you’re behind on payments, served with foreclosure papers, or trying to avoid a sheriff’s sale, mediation can feel like a lifeline—but only if you use it the right way.
Call (312) 775-0980 or request a free case analysis to get plain-English next steps and a plan built around your deadlines (no hype, no guarantees—just clarity).
January 20, 2026
Notice of Default vs. Foreclosure Lawsuit: What’s the Difference in Illinois?
Mortgage letters can feel like “the foreclosure already started.” Court papers feel like “it’s over.”
In Illinois, those are two different moments with two different levels of urgency—and two different kinds of leverage.
Call (312) 775-0980 or request a free case analysis to get plain-English next steps based on what you actually received.
In Illinois, those are two different moments with two different levels of urgency—and two different kinds of leverage.
Call (312) 775-0980 or request a free case analysis to get plain-English next steps based on what you actually received.
January 15, 2026
Selling Your 2–4 Flat While in Foreclosure: Short Sale, Regular Sale, or Investor Buyout?
If you own a 2–4 flat and a foreclosure case is already pending, selling can still be a smart exit—but only if the foreclosure timeline and the sale timeline stay synchronized.
Call (312) 775-0980 or request a free case analysis to get clear next steps on your best path: a regular sale, a short sale, or a properly-structured investor buyout.
January 13, 2026
Meet Mahmoud Faisal Elkhatib
Mahmoud Faisal Elkhatib—known as The Bow Tie Attorney—helps Chicago property owners and small landlords protect what they’ve built when the stakes get real. His work focuses on strategic foreclosure defense and closely related real estate matters, including disputes, lender/servicer issues, and transactions that need to close cleanly. Clients come to Mahmoud when they need more than generic advice: they want a plan based on deadlines, leverage points, and how Cook County cases actually move. The goal is simple—clarity, options, and a strategy built for real outcomes.
January 12, 2026
Mortgage Litigation in Chicago & Illinois: When Your Mortgage Company Gets It Wrong
When a mortgage servicer makes mistakes, the damage can snowball: late fees, escrow shocks, credit hits, and even foreclosure pressure.
This guide explains mortgage litigation in plain English—what it is, when it matters, and what to do next if your mortgage company gets it wrong in Chicago, Cook County, or anywhere in Illinois.
January 12, 2026
Cook County Sheriff Sale in Chicago: What the Notice Means and What to Do Next
Got a Cook County sheriff sale notice—or worried one is coming? You may still have options, but timing matters.
Call (312) 775-0980 to review your paperwork and get clear next steps.
Informational only, not legal advice. Results vary.
Call (312) 775-0980 to review your paperwork and get clear next steps.
Informational only, not legal advice. Results vary.
January 7, 2026
Foreclosure Attorney Chicago: Stop Foreclosure, Sheriff Sale Help, and Your Options
Behind on payments, served with foreclosure papers, or worried about a sheriff’s sale?
Quick form tip: Add a field for “Sale date (if any)” so we can triage urgency immediately.
January 5, 2026
Foreclosure Summons in Illinois: What It Means and What to Do Next
If you’ve been served foreclosure papers, you’re not alone—and you’re not out of options.
This guide explains what a foreclosure summons and foreclosure complaint usually mean in Illinois, what early deadlines tend to control the case, and what to do next to protect your time, money, and leverage.
January 2, 2026
Foreclosure Defense in Illinois: Protect Your Leverage, Protect Your Options
Illinois foreclosure is a court case—and timing matters. EV Häs, LLC Attorney at Law helps homeowners and property owners respond with strategy, not panic: we pinpoint your stage, pressure-test the lender’s filings, and recommend the next best move based on your deadlines.
Educational only; not legal advice. A case-specific consult is required for real guidance.
January 2, 2026
Mortgage Litigation: When Your Mortgage Company Gets It Wrong
Mortgage litigation is about fixing real harm—servicing errors, broken promises, and unfair foreclosure tactics.
When a servicer mishandles payments, misapplies escrow, loses a modification package, or pushes foreclosure while you’re actively trying to resolve the loan, your options may include more than “just call them again.” This page explains what mortgage litigation is, when it makes sense, and how we approach it in Illinois. Educational only; not legal advice.
January 2, 2026
Building Code Violations in Chicago: What the Notice Means and How to Defend It
Chicago building code tickets can move fast—and the penalties can get expensive.
This guide explains what typically happens after an inspection, what defenses the Chicago Municipal Code recognizes, and how to build a clean, credible response before your administrative hearing. Educational only; not legal advice.
January 2, 2026
Asset Protection in Illinois: Protect What You’ve Built (The Right Way)
Asset protection is not about hiding assets. It’s about building a legal structure that reduces avoidable risk before a problem shows up—especially for homeowners, landlords, business owners, and professionals.
This page explains the core tools (insurance, entity structure, titling, contracts, and planning) and the biggest mistakes that can make a situation worse. Educational only; not legal advice.
January 2, 2026
Kane County Tax Appeal: Deadlines, Evidence, and How to File Correctly
Kane County tax appeals are deadline-driven and evidence-driven—and one of the biggest traps is assuming your deadline is the same as someone else’s.
This guide explains how Kane County appeals work, why township deadlines vary, what evidence the Board expects, and what to do if you want to appeal beyond the county level. Educational only; not legal advice.
January 2, 2026
Will County Tax Appeal: Deadlines, Evidence, and What Happens Next
Will County property tax appeals are deadline-driven and evidence-driven—and the process has two different “30-day clocks” owners often confuse.
This guide explains (1) how Will County Board of Review appeals typically work after you receive your notice, and (2) what happens if you take the next step to the Illinois Property Tax Appeal Board (PTAB) after a final Board of Review decision. Educational only; not legal advice.
January 2, 2026
Elevate Your Real Estate Experience in Chicago
Real estate is supposed to feel exciting—until the paperwork gets confusing, the timeline gets tight, or a “small” title issue turns into a closing-day emergency.
We help buyers, sellers, investors, and agents move through Chicago-area transactions with clarity and control, so you’re not guessing at the table or finding surprises after the deed is recorded.
January 1, 2026
Be Your Client’s Advocate
Your client doesn’t just need a closer — they need an attorney who spots deal-killers early, explains the moving parts in plain English (and Spanish), and protects them when the transaction starts getting complicated.
Here’s how EV Häs, LLC Attorney at Law supports Chicago-area brokers by keeping deals clean, timelines clear, and surprises to a minimum.
January 1, 2026
Lake County Tax Appeals: How to File the Right Way (Without Guessing)
Lake County gives property owners a real process to challenge an assessment—but it is deadline-driven and evidence-driven.
This page breaks down what the Board of Review looks for, when you must contact your township assessor first, how the 30-day filing window works, and how to choose a hearing type (including letter review and Zoom). For educational purposes only; not legal advice.
January 1, 2026
DuPage County Tax Appeals: How to Challenge an Over-Assessment
DuPage property owners get an annual opportunity to appeal an assessment—but the filing window is tied to your township’s publication date, and it can close fast.
This page explains the DuPage process in plain English: the 30-day deadline, what to do before you file, what evidence the Board expects, and what happens if you want to take the appeal further. Educational only; not legal advice.
January 1, 2026
Cook County Property Tax Appeal: A Clear Evidence-First Guide
A tax appeal is not a rant or a guess. It is a well-labeled evidence packet that makes it easy for the reviewer to see (1) what you are asking for and (2) why your numbers make sense.
This page breaks down what to gather, how to present it, and the common mistakes that quietly sink otherwise valid appeals.
January 1, 2026
Tax Process Overview: How Illinois Property Taxes Are Set (and Where You Can Challenge Them)
Property taxes feel mysterious until you break them into two levers: the tax levy (what local governments need to collect) and the assessment (your property’s share of that total).
This guide walks Chicago-area owners through the process in plain English—how values and rates connect, what the “equalization factor” is doing in the background, and what an appeal actually looks like when you do it correctly.
January 1, 2026
Real Estate Tax Appeals in Chicago
If your property taxes jumped—or your assessment feels disconnected from reality—you may have options.
This guide explains how Illinois tax appeals work in plain English, what evidence matters most, and how to approach Cook County (and surrounding counties) without wasting a filing window. Informational only; not legal advice.
January 1, 2026
What to Expect at the Closing Table
Closings move fast—and the stress usually comes from not knowing what’s normal.
This guide walks you through what typically happens from contract to closing day, what you should review before you sign, and what to bring so you show up prepared (and avoid last-minute surprises).
For educational purposes only. Not legal advice. Every deal is different.
This guide walks you through what typically happens from contract to closing day, what you should review before you sign, and what to bring so you show up prepared (and avoid last-minute surprises).
For educational purposes only. Not legal advice. Every deal is different.
January 1, 2026
Bifurcated Title in Illinois
Bifurcation of title is when the buyer chooses a different title company than the one selected by the seller’s attorney, so the buyer’s side of the title services is handled by the buyer’s preferred provider. When the buyer is obligated to pay for title insurance, Illinois law supports the buyer’s right to choose the title insurance company and agent. Savings vary by transaction, lender requirements, contract terms, and timing. For educational purposes only, not legal advice.
January 1, 2026
Real Estate Closing Attorneys in Chicago, IL
Every real estate deal is more than paperwork. It’s your home, your investment, your risk exposure, and your future financial stability.
EV Häs, LLC Attorney at Law helps buyers, sellers, brokers, and investors close with confidence—by catching hidden problems early, negotiating stronger terms, and making sure your transaction doesn’t turn into a lawsuit later.
For educational purposes only. Not legal advice.
EV Häs, LLC Attorney at Law helps buyers, sellers, brokers, and investors close with confidence—by catching hidden problems early, negotiating stronger terms, and making sure your transaction doesn’t turn into a lawsuit later.
For educational purposes only. Not legal advice.
January 1, 2026
The Foreclosure Timeline With a Qualified Foreclosure Attorney
The foreclosure timeline is not “fixed.” In Illinois, the pace of a case often depends on whether you have counsel—and whether that counsel knows how to use both litigation and negotiation to protect your rights and preserve options.
This page explains what the timeline can look like when a qualified foreclosure defense attorney is actively challenging the lender, preventing default momentum, and building leverage for the best available outcome.
For educational purposes only. Not legal advice. Timelines vary by county, judge, loan type, and the facts of your case.
This page explains what the timeline can look like when a qualified foreclosure defense attorney is actively challenging the lender, preventing default momentum, and building leverage for the best available outcome.
For educational purposes only. Not legal advice. Timelines vary by county, judge, loan type, and the facts of your case.
January 1, 2026
The Uncontested Foreclosure Timeline in Illinois
An “uncontested” foreclosure is what the process can look like when a homeowner doesn’t meaningfully engage the case.
This timeline is a practical, plain-English roadmap of what often happens next—so you can recognize the pressure points early and avoid letting “default momentum” make your decisions for you.
For educational purposes only. Not legal advice. Timeframes are estimates and vary by county, judge, loan type, and the facts of your case.
This timeline is a practical, plain-English roadmap of what often happens next—so you can recognize the pressure points early and avoid letting “default momentum” make your decisions for you.
For educational purposes only. Not legal advice. Timeframes are estimates and vary by county, judge, loan type, and the facts of your case.
January 1, 2026
What Happens After Foreclosure in Illinois?
For most homeowners, the hardest part isn’t the word “foreclosure.” It’s the unknown: “When do I have to leave?” “Do I still owe money?” “What happens to tenants?”
This guide explains what typically happens after a foreclosure sale—confirmation, possession, eviction timing, deficiency risk, and the practical steps that help you land as safely as possible.
For educational purposes only. Not legal advice.
This guide explains what typically happens after a foreclosure sale—confirmation, possession, eviction timing, deficiency risk, and the practical steps that help you land as safely as possible.
For educational purposes only. Not legal advice.
January 1, 2026
The Foreclosure Timeline in Illinois
Foreclosure in Illinois is a court process with a rhythm—service, hearings, motions, judgment, and (sometimes) a sale.
If you understand what each stage means, you can stop guessing and start using time wisely—whether your goal is to keep the home longer, negotiate a workout, or plan a clean exit.
For educational purposes only. Not legal advice. Timelines vary by county, judge, loan type, and the facts of your case.
If you understand what each stage means, you can stop guessing and start using time wisely—whether your goal is to keep the home longer, negotiate a workout, or plan a clean exit.
For educational purposes only. Not legal advice. Timelines vary by county, judge, loan type, and the facts of your case.
January 1, 2026
What Are My Foreclosure Options in Illinois?
If you’re facing foreclosure in Chicago or the surrounding counties, you usually have more than one path.
This guide breaks down the most common options by stage—before a lawsuit, after you’re served, and when a sale date is on the horizon—so you can stop guessing and start making intentional moves.
For educational purposes only. Not legal advice. Every case is different.
This guide breaks down the most common options by stage—before a lawsuit, after you’re served, and when a sale date is on the horizon—so you can stop guessing and start making intentional moves.
For educational purposes only. Not legal advice. Every case is different.
January 1, 2026
What Is Mortgage Foreclosure in Illinois?
Foreclosure isn’t a scary mystery—it’s a lawsuit. In Illinois, the lender files a court case asking for permission to sell the property to pay the mortgage debt. Once you know what the paperwork means and what the court is watching for, the next steps get a lot clearer.
Informational only; not legal advice. Outcomes and timelines vary by case.
December 31, 2025
Pay Up or Move Out? A Zombie Mortgage Story—Chicago Edition
A reported case shows how a “quiet” second mortgage or HELOC can come back to life years later under a new company, with back interest and hard deadlines attached.
This article walks Chicago-area homeowners through the pattern behind “zombie” seconds, the red flags to watch for in letters and phone calls, and what our team would do in the first 48 hours so you are not deciding between “pay up” and “move out” alone.
Ready to Get Clear Next Steps?
Tell us what notice you received or your next court date. We’ll confirm where you are in the process and recommend your strongest next move—without panic or guesswork.
We typically respond the same business day or the next business day.